Dan Immergluck
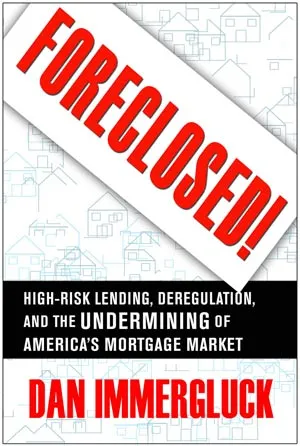
Foreclosed
Unlike many books on the mortgage and financial crises in the trade press, Foreclosed focuses much more on the damage that high-risk lending markets imposed on neighborhoods and communities. I pay particular attention to the public policy debates that evolved in the late 1990s and early 2000s over increasing regulation of high-risk lending.
Over a large portion of the twentieth century – from the 1930s through the early 1990s – the federal government’s active involvement in mortgage markets, both as regulator and investor, provided for generally sound, risk-limiting home finance. The penultimate example of this public-private partnership was the 30-year, fixed-rate fully amortizing mortgage that was fairly conservatively underwritten, typically by lenders and investors that had a significant stake in the performance of the loans that they underwrote.
Over the 1980s and 1990s, the U.S. mortgage market moved away from a financial system that, despite some significant flaws, generally delivered safe and sound mortgage finance to one that shifted risk to borrowers, and, as a byproduct, increased risk to the financial system overall. This transition happened first via the government-sponsored entities Fannie Mae and Freddie Mac, and then later through higher-risk investors in private label securities.
Problems in subprime mortgage markets were evident well before 2000. The book documents how policymakers made explicit decisions to let the mortgage industry have free reign in aggressively pushing dangerous products, particularly in minority and modest-income communities. Federal policymakers in both the executive and legislative branches not only failed to expand regulatory supervision over a new high-risk loan sector, they aggressively preempted states that attempted to step into the breach.
Beyond its implications for the literature on housing and mortgage markets and related public policy, Foreclosed fits into a broader literature on the political economy and the role of free-market ideology in the formation of public policy and regulation and, more particularly, of housing and urban policy.
Editor: Erind Pajo
Foreclosed
Dan Immergluck Foreclosed: High-Risk Lending, Deregulation, and the Undermining of America’s Mortgage Market Cornell University Press 272 pages, 6 x 9 inches ISBN 978 0 8014 4772 3
Available here →June 24, 2009
20090624-immergluck-foreclosed-high-risk-lending-deregulation-mortgage-mark-2
The wide angle
The rest of this thread
Stanley Leary
Dan Immergluck
Dan Immergluck is Associate Professor in the City and Regional Planning Program at Georgia Institute of Technology in Atlanta, where he teaches housing policy, real estate finance, and quantitative methods. Dr. Immergluck’s research focuses on housing markets, mortgage and real estate finance, neighborhood change, and related topics. Besides Foreclosed he has authored two previous books, including Credit to the Community: Community Reinvestment and Fair Lending Policy in the U.S. (M.E. Sharpe, 2004). Dr. Immergluck has been widely published in scholarly journals as well as in more applied venues, and widely cited in the recent policy debates surrounding the mortgage crisis. He has testified before Congress, the Federal Reserve Board, and state and local legislatures. Before becoming a full-time scholar, Dr. Immergluck was a community developer and an applied researcher; his work is grounded in a fundamental pragmatism and characterized by an inductive approach to understanding how markets and policymakers behave.
Pull this thread
pulls againstpulls alongside
The subprime collapse was made by policy, deregulation since the early 1980s and capital markets wired directly to homeowners.
Against JL · Governments cannot dictate how venture markets evolve, and most attempts have wasted billions. On: Voluntary and market mechanisms can supply the public goods that states otherwise supply
Against JS · The prohibition on hosting kleptocrats' money fails for structural reasons, and the remedy is to recruit the profit motive. On: Voluntary and market mechanisms can supply the public goods that states otherwise supply
Alongside BS · Socially responsible investing does not work and cannot, and the $30 trillion industry built on it is selling an illusion. On: Voluntary and market mechanisms can supply the public goods that states otherwise supply
Alongside JJ · The civil RICO intervention in the Teamsters worked, and government intervention for union democracy makes a stronger union. On: Voluntary and market mechanisms can supply the public goods that states otherwise supply
Alongside PB · Corporate support for Black culture is diversity capital, an asset the firm accumulates for itself. On: Voluntary and market mechanisms can supply the public goods that states otherwise supply
Alongside MP · Making the abutting property owner responsible for the public sidewalk is the central error of American sidewalk law. On: Voluntary and market mechanisms can supply the public goods that states otherwise supply
Nearby DD · Dodd-Frank does not permit the safe resolution of a distressed systemically important financial institution.
Know something the rest of us don't?
Most threads on Rorotoko begin with our invitation. Any thread can begin with a proposal: you write it with the same prompts every thread answers, and we review it.
Propose a thread →